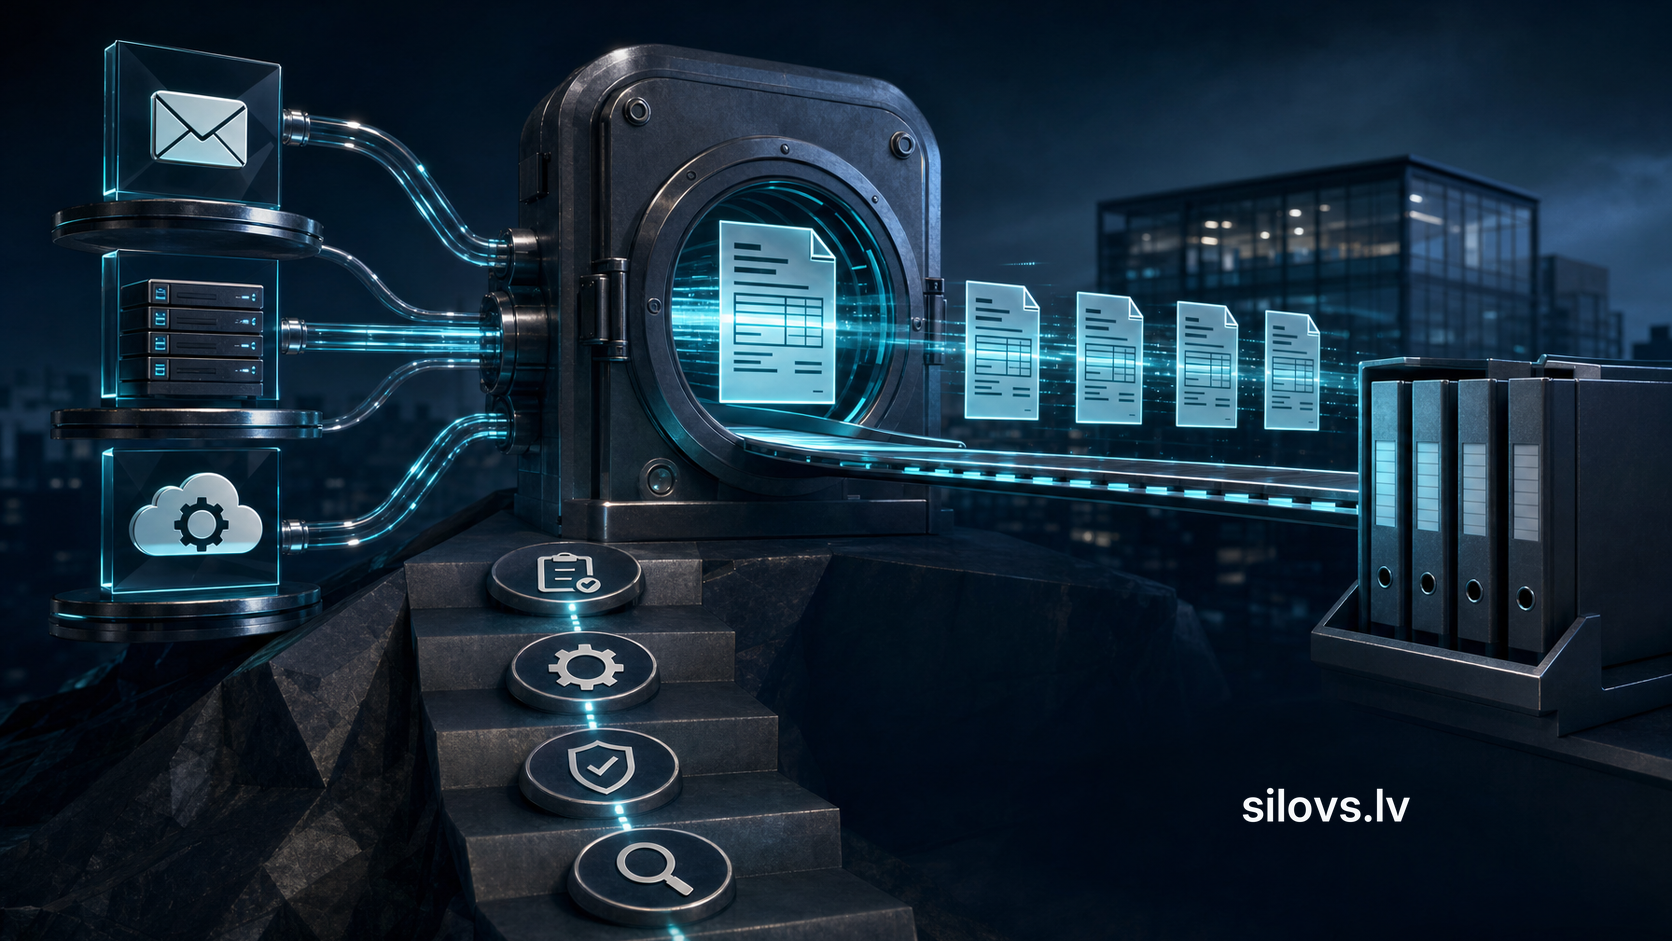
Choose e-invoice integration based on recipients’ requirements, the amount of manual work and the controls you need, not just the cost of sending an invoice. E-address is an environment for official communications and document delivery; an e-invoice operator provides a document exchange service; an accounting system connection enables data to move through the accounting process. These options are not necessarily mutually exclusive: a system can connect to an operator that handles onward delivery.
If document volumes are low and a designated employee can reliably monitor the workflow, manual processing through the chosen channel may be sufficient. If invoice data is being re-entered, delivery status is lost or recipients have different requirements, assess a system connection and, potentially, an operator’s service. The outcome should be a verifiable workflow from invoice creation through to receipt and accounting, not merely the ability to upload a file.
A structured e-invoice is not a PDF attachment
A structured e-invoice is an electronically prepared invoice containing data in an agreed, machine-readable structure that allows automated processing. An ordinary PDF invoice sent by email is not a structured e-invoice; an electronic signature alone does not turn a PDF into a structured document either.
Distinguish between three things: the invoice data, its technical format and the delivery channel. An XML file alone does not demonstrate compliance: you need to check the required structure, the data content and the applicable validation rules.
EN 16931 describes the semantic data model for an e-invoice. Peppol BIS Billing 3.0 is a more specific e-invoice exchange specification with its own rules. The Peppol documentation is a technical reference point if the chosen solution uses this specification, not evidence that all Latvian e-invoices must be sent through the Peppol network.
A business needs to know not only whether its software exports XML, but also whether the recipient can accept and process the document without losing data.
E-invoice integration: three layers that can work together
When comparing options, separate document transport from processing within the business. Otherwise, you may pay for convenient sending while leaving all the accountant’s manual work untouched.
|
Solution layer |
What it addresses |
When to consider it in particular |
What to check separately |
|
E-address |
An environment for sending and receiving official documents |
The recipient uses this channel; a manual workflow is manageable |
Document preparation, import into the accounting system and storage |
|
E-invoice operator |
Document exchange and the additional services specified in the contract |
There are different recipients or formats, or centralised support is needed |
Compatibility, validation, statuses, data export and pricing |
|
Accounting system connection |
Exchange of data and statuses with the accounting system |
Re-entering data needs to be reduced and a regular document flow needs to be controlled |
The actual delivery channel, error handling and maintenance |
E-address can also be used in an automated solution if the chosen connection supports it. Using a portal manually and integrating systems are not the same thing. Check e-address capabilities and access arrangements on the official Latvija.gov.lv portal.
Do not assume that an operator’s offering includes format conversion, an archive or the ability to reach every trading partner. These functions must be clearly described as part of the service.
Assess incoming and outgoing invoice requirements separately. Software may send invoices well but merely display received invoices in a list without transferring them into accounting entries. During a demonstration, ask to see both flows through to the outcome your business needs, rather than just a successful file transfer.
Establish your obligations before choosing a channel
This is a guide to choosing a solution, not a calendar of current implementation deadlines. The latest versions of the sources and the services’ features have not been checked in real time here. Before implementation, check the version of the Accounting Law currently in force and its transitional provisions, as well as the State Revenue Service (VID) information on e-invoices.
The trading partner’s status, the type of transaction and the transitional provisions may affect the applicable obligation. Consult an accountant or tax adviser about the requirements for a particular transaction; these should not be determined from software marketing material.
Before preparing a technical specification, answer three questions:
- Which of the business’s documents and trading partners are subject to the structured e-invoice requirement?
- What format and delivery route are acceptable to the particular recipient?
- Is there a separate obligation to submit invoice data to VID, and which party involved in the solution fulfils it?
Sending an invoice to a customer and submitting data to VID are separate tasks in the process. Do not assume that one action automatically fulfils the other. If a supplier promises both, ask for a demonstration of the statuses and error messages for both actions. Also keep a record of the agreement on who checks how regulatory changes affect the configuration.
Prepare a consistent brief for suppliers
Describe your current invoice workflow in a single working document. Specify the invoicing system, accounting system, recipient groups, channels used, document volume and its fluctuations. Include incoming invoices and the points where someone currently re-enters or corrects data.
There is no universal invoice count above which integration necessarily pays for itself. A few complex invoices with many line items may require more work than a large set of simple documents. Alongside volume, therefore, record processing time, common exceptions and the consequences of delays.
Add representative, safely anonymised document samples: a standard invoice, a credit note and non-standard cases relevant to your operations. If you use attachments, currencies or purchase order references, include those too. Using the same set of samples helps you compare proposals based on actual performance rather than feature names.
Implementation in six verifiable steps
1. Define the data source and field mapping
Agree which system is the primary source for the invoice number, trading partner details, line items, amounts and payment due date. If an invoice originates in a sales system but accounting takes place elsewhere, clearly define where corrections may be made and how they are passed on.
Create a field-mapping table covering the source field, target field, transformation rule and method of verification. Pay particular attention to VAT (PVN) categories, rounding, units of measure, discounts and contract or purchase order references. Not all these fields are universally mandatory, but a particular recipient may require them for its own process.
Do not treat a registration number as an automatic substitute for the recipient identifier used by a particular network. Check the data needed to address the delivery against the requirements of the chosen channel. The accountant should check the economic meaning of the data, while the integration developer should check its technical transfer.
2. Agree on the format and connection
Record the supported format, its version, validation rules, attachment limits and authentication arrangements. The agreement must cover the entire route to the recipient, not just export from the first application.
An API is not mandatory in every situation. Controlled file exchange may be sufficient if periodic imports are acceptable and processing arrangements are clear. An API is worth considering when regular automated exchange and status updates are needed, but it also requires error handling and maintenance.
If the operator converts the format, check that all values important to the business and the recipient are preserved. Successful conversion means more than producing a file that can technically be opened. Also agree on notification before changes to formats or interfaces, and on retesting after updates.
3. Separate delivery and accounting statuses
An internal model might follow this sequence: created → validated → handed over to the channel → delivery confirmed. Add a recipient processing status only if the particular solution actually provides it. The statuses ‘posted to the accounts’ and ‘paid’ must come from the systems that record those events.
A successful API response may mean only that the request has been accepted. It does not always confirm document delivery, acceptance by the recipient or posting to the accounts. For each status, describe its source, meaning and when action is required if the next event has not been received. An employee must be able to find a particular invoice and understand its current status without access to the developer’s technical logs.
4. Prevent duplicate processing
A timeout can occur after the other system has already received the invoice. Resending must therefore not automatically create a second invoice or accounting entry. Use an idempotency mechanism and retain the link between the business’s document identifier, the exchange identifier and the external system’s response.
The invoice number alone is not always sufficient to detect a duplicate, especially for incoming invoices from different suppliers. Choose duplicate-detection criteria that reflect document numbering and business rules.
A correction or credit note needs an explicitly defined link to the original document and separate processing, rather than silently overwriting the original entry. During testing, repeat both a sending request and receipt of the same document through a repeat delivery route.
5. Create an exception queue
Distinguish between a data error, a temporary connection failure and an uncertain delivery outcome. Resending will not resolve a missing mandatory field. If the outcome is uncertain, check whether the document has already been accepted before manually resending it.
Each exception must have an owner, an action and a record of its resolution. Also designate someone to cover absences. The fallback process must not create a parallel, untracked invoice flow by email. If manual sending is permitted, its outcome must be reflected in the overall records so that the automation does not send the document again later.
6. Test the whole process, not just the export
Include a valid document, a rejected document, a missing recipient-required reference, a credit note, an attachment, a repeated request and a connection timeout in your tests. The accountant must also check the amounts, how VAT (PVN) treatment is represented and the rounding. Technical validation does not replace an accounting assessment of the transaction.
For each test, record the expected result in advance: what appears in the sender’s system, what the other party receives and what entry is created in the accounts. Use the supplier’s test environment if one is available; if not, agree a safe testing procedure with the parties involved.
Separately test the operator or channel becoming unavailable and recovering. After a disruption, it must be possible to reconcile the unprocessed documents rather than simply restarting the entire flow. The test must provide demonstrable evidence that documents and statuses match in both systems.
Limitations, security and document retention
Integration does not fix poor-quality master data or turn every received invoice into an expense that can be approved automatically. If the business requires transaction checks or expense approval, retain those controls even after a technically successful import. Design payment preparation and approval as a separate stage with its own responsibilities.
Give the system account only the permissions it needs. Store API credentials securely, make provision for replacing them and do not use a shared employee account for the entire integration. Logs should not unnecessarily contain copies of full invoice contents or access secrets.
Invoices may contain personal data. If such data is processed, assess the parties’ roles, access rights, processing conditions and safeguards in line with the General Data Protection Regulation. Roles are determined by the actual processing, not merely by what the supplier is called.
Retain the structured document sent or received, the necessary attachments and evidence of processing; keep a visual representation if it is needed for work. Set retention periods according to the applicable requirements. Do not treat an operator’s portal as the business’s archive without a clear agreement on retention periods, availability and export after the contract ends. A backup and a long-term archive are not the same thing.
Compare total costs and the boundaries of responsibility
Compare proposals over the same chosen period, separating implementation, subscriptions, per-document charges, maintenance and the manual work that remains. Show data export and service-switching costs separately. Cheap sending may not mean a low-cost workflow if an employee then has to correct every import.
Estimate manual work using observations of your own process: document counts, actual processing time and exception frequency. Do not replace these with a supplier’s generic savings promise. Allow time in the calculation for monitoring, support communications and testing changes too.
Specify in the contract or technical brief who maintains the field mapping, responds to errors and adapts the solution to specification changes. Request concrete support arrangements: where to report a problem, what data is needed to investigate it and who coordinates cooperation between the operator and the accounting software supplier. The business’s accountant should not be left as the sole intermediary in a technical dispute between two services.
How to decide after a trial
Start with a limited but representative set of documents and trading partners. This must not be merely a selection of the simplest invoices: the trial needs to include exceptions that matter to the business. Before starting, agree what outcome will allow wider use and under what circumstances the flow must be stopped.
When calculating the proportion of automatically processed documents, count only those that have reached the predefined final status without manual data correction. For an outgoing invoice, this might be confirmed delivery; for an incoming invoice, import and verification in the accounting system. Measure the two flows separately.
Also monitor processing time, reasons for rejection, the age of stuck documents and the time spent on manual corrections. A good overall success rate must not hide a few invoices that have remained undelivered for a long time.
Before wider implementation, check:
- Can every document be traced from its source to the intended final status?
- Does repetition avoid creating a duplicate, and can an uncertain status be resolved?
- Does the recipient receive the data it needs, rather than just a technically valid file?
- Is there a responsible person and a controlled fallback process when a failure occurs?
- Can the business export documents and the necessary evidence of processing?
If any answer is unclear, refine the solution before increasing the volume. Acceptance criteria must demonstrate a manageable workflow, not simply that the connection worked once.
Next step
Before asking for a price, prepare document samples, recipient requirements and a diagram of both invoice flows. With this material, you can make an informed decision about whether configuring the existing software’s capabilities is enough, an operator is needed or a separate connection must be developed.
If you need to choose the type of connection, the next article to read is ‘When a business needs API integration and when simpler data exchange is enough’. For the technical design of repeat processing, see ‘Idempotency in integrations: how to prevent duplicate invoices and orders’.